UK House Prices Rise Again After Months Of Decline
UK house prices have risen for the first time since May, according to fresh market data released on September 21. The average property coming onto the market increased in price by 0.7 percent in September compared with August. The increase was equal to about £2,441. The latest rise marks a change after several months of
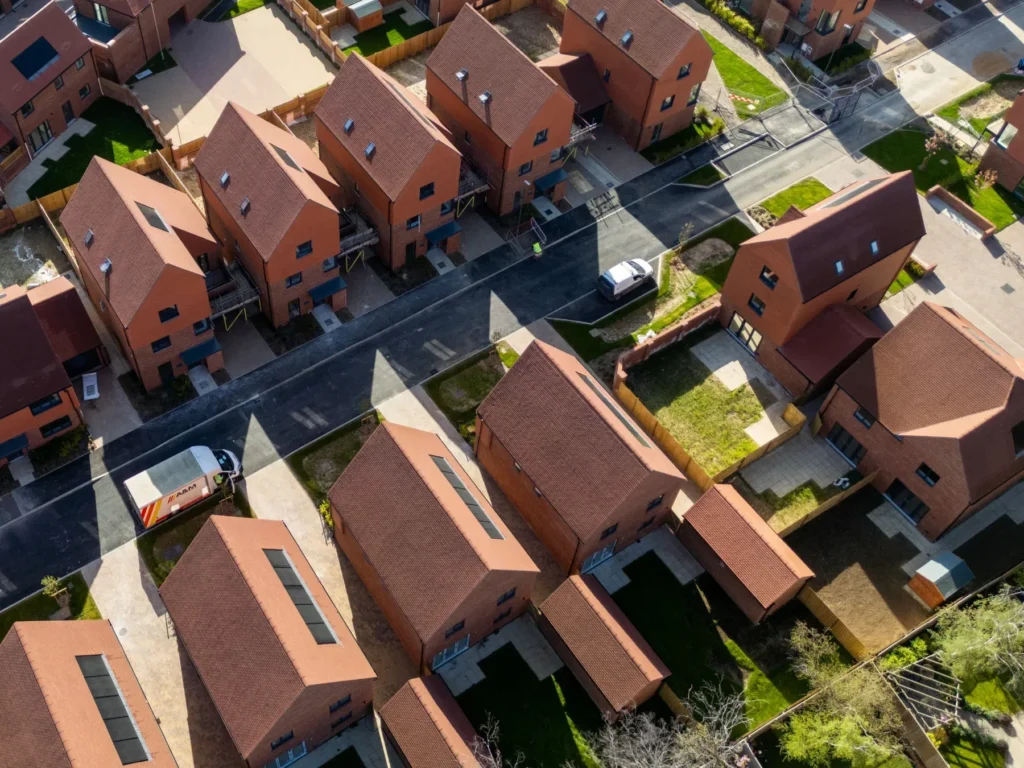
UK house prices have risen for the first time since May, according to fresh market data released on September 21. The average property coming onto the market increased in price by 0.7 percent in September compared with August. The increase was equal to about £2,441. The latest rise marks a change after several months of weaker price movement in the housing market.
House prices are closely watched because the property market affects household wealth, consumer confidence and the wider economy. The September increase does not mean every property became more expensive. Average asking prices can change because of the type and location of homes entering the market.
Still, the rise provides a new signal about the direction of the UK housing market.The property market has been under pressure from borrowing costs and wider economic uncertainty. Mortgage rates affect how much buyers can afford and can influence demand for homes.
When borrowing becomes more expensive, some potential buyers delay purchases or look for cheaper properties. This can put pressure on house prices. The latest data suggest that sellers are now placing homes on the market at higher average asking prices. The change comes as the UK economy faces wider questions about inflation, interest rates and household spending.
The Bank of England has kept close attention on economic conditions as it considers future interest rate decisions. Mortgage costs are strongly linked to the wider interest rate environment. For buyers, the latest rise may add to concerns about affordability. A higher asking price can increase the deposit and mortgage needed to purchase a property. For sellers, the increase may provide some support after a period of weaker market conditions.
The housing market also differs sharply across the UK. Prices in London, northern England, Scotland, Wales and other regions can move at different speeds. National figures therefore do not show the full picture for every buyer or seller.
The September data are also based on properties coming to the market rather than completed sales. Asking prices can later change during negotiations.
This means the figures should be treated as an early measure of market conditions rather than a final measure of completed transactions.
The market will be watched closely over the coming months. Investors, lenders and households want to know whether the rise will continue or whether prices will weaken again. Economic conditions will remain important. Employment, wages, inflation and borrowing costs all influence the ability of households to buy homes.
The government is also monitoring housing supply and affordability. A shortage of homes in some areas can put upward pressure on prices even when wider demand is uncertain.
For first-time buyers, the picture remains mixed. Higher prices can make saving for a deposit harder, while changes in mortgage rates can affect monthly payments.
For homeowners who are already on the property ladder, rising prices can increase the value of their homes. However, this does not always improve household finances unless they sell or refinance. The September rise therefore offers one positive signal for the housing market but does not settle the wider affordability debate.
Further data over the autumn will show whether the increase becomes a longer trend. For now, the UK market has recorded its first monthly rise in average asking prices since May, giving the housing sector a new development to watch.